Risk Managers
Defensible
Quant Risk
Removing subjectivity from oversight. We enable risk managers to move beyond qualitative assessments to defensible, quantitative analysis.
VaR / CVaR
Pooled downside and tail loss (VaR 1%/5%, CVaR) from a single holding to the total fund.
LGD Modeling
Calculate Loss Given Default and probability of equity injection needed.
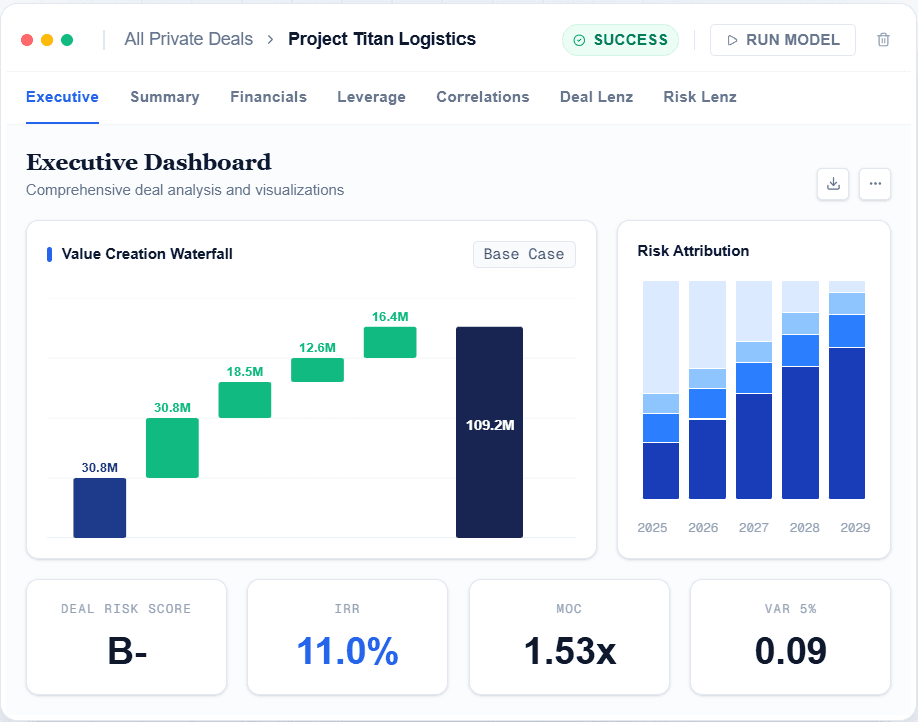
Move beyond qualitative assessments to defensible, quantitative analysis.
1. Tail Risk Indicators
Monitor the probability of negative returns and covenant breaches (DSCR, Net Leverage) in real-time. Anticipate defaults before they impact fundamentals.
2. Risk Attribution
Identify whether risk is driven by revenue volatility, operating leverage, or financial structure. Stacked attribution reveals top 3 primary risk factors.
3. Factor Sensitivities
Growth, interest-rate, currency, and inflation sensitivities computed at holding, book, and fund level — one factor lens from a single deal to the total fund.
Governance & Reporting
Audit Trails
Complete history of risk assessments with data lineage for every quantitative metric.
Exception Reporting
Automated alerts for deals exceeding established risk thresholds or drifting from fund mandate.
We move Risk from a skeptic's perspective to a proactive deal partner by linking Value-at-Risk directly to fundamental cash flow assumptions.